

Yuan hits four-year high, posing headwinds for Chinese economy
Sep 21, 2026, 10:07 am


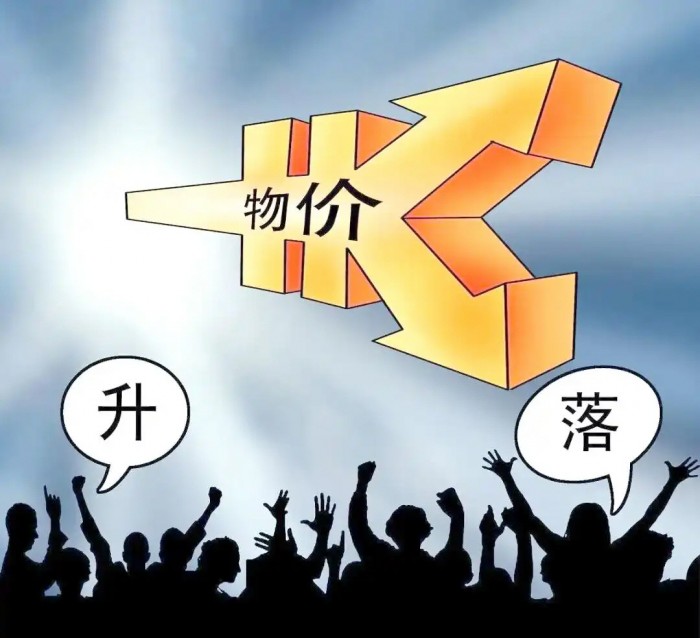 |
| A cartoon by a Chinese media outlet illustrates how fluctuations in the yuan affect prices. A stronger yuan has the advantage of lowering import costs. / Economic Daily |
The Chinese yuan, or renminbi, has continued to climb to its strongest level in four years and two months, supported by exceptionally strong exports and unchanged interest rates. The trend is unlikely to reverse significantly anytime soon. The currency is enjoying a period of notable strength, but that may prove to be a negative for the broader Chinese economy.
According to recent reports by Chinese media including Economic Daily, the yuan was still trading near 7 per U.S. dollar at the end of last year. At the time, a sustained move below the psychologically important 7-yuan threshold appeared difficult.
However, strong export performance and the resulting large net inflows of dollars changed that picture, pushing the yuan through the 7-per-dollar level and continuing to support appreciation.
The People’s Bank of China’s decision to keep the one-year loan prime rate at 3.0%, leaving it unchanged for 16 consecutive months, also added momentum to the currency’s rise.
By mid-September, the yuan had strengthened to 6.6957 per dollar, its highest level since July 2022. Further appreciation is widely expected, with some in Beijing’s financial sector projecting that it could reach 6.65 per dollar by year-end.
Beyond strong exports and steady interest rates, other factors are also supporting the yuan.
One is the Iran war, which has boosted demand for the yuan alongside the dollar. Another is Iran’s push to settle crude oil payments in yuan, an effort seen as challenging the dollar-centered global settlement system.
A stronger yuan is not entirely negative for China’s economy. Lower import costs can ease the burden on consumers and improve living standards. It can also raise China’s GDP and per capita GDP when measured in dollar terms.
But exporters are likely to face growing pressure as their goods become less price-competitive overseas.
Cheaper imports could also deepen China’s chronic deflation problem by placing further downward pressure on domestic prices. With the economy already struggling with weak domestic demand and the fallout from the bursting of the property-sector bubble, a stronger yuan could add another source of strain.
Even so, further appreciation may be difficult to avoid.
The U.S., which helped drive a sharp rise in the Japanese yen through the Plaza Accord more than 40 years ago, has also maintained pressure on China over the value of the yuan.
That is why some in Beijing’s financial community believe China could be heading toward an era of a “super yuan.”
Hong Soon-do
Most Read
-
1
Celltrion’s Omlyclo gains ground in major European..

-
2
Trump demands rates fall below 1% as Fed hikes for..

-
3
Trump makes $1 trillion bet ahead of midterm elect..

-
4
Iran resumes ballistic missile production, assembl..

-
5
Samsung Electronics, Mistral AI to jointly develop..

-
6
Trump warns countries not helping U.S. must pay re..

-
7
Seoul faces triple squeeze over troop deployment t..

PEOPLE


-
Address : In-Young Bldg., 34, Uisadang-daero 1-gil, Yeongdeungpo-gu, Seoul
Copyright by ASIATODAY CO., LTD. All rights resereved