

[Reporter's Note] Banks pay hundreds of billions of won to law firms every year — how to make it worth it
Aug 14, 2026, 10:08 am


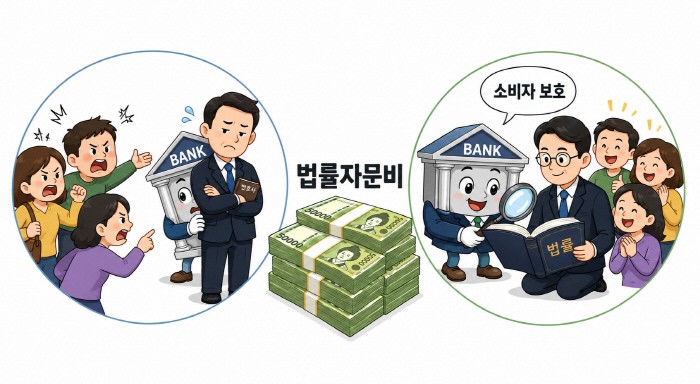 |
| This image was generated by AI. |
 |
Banks are steady clients for law firms. From designing financial products to issuing bonds and doing business overseas, it's hard to find work that doesn't require legal review. As a result, major commercial banks spend a significant amount — hundreds of billions of won annually — on outside legal counsel.
What's notable is that the nature of this spending is gradually shifting. In the past, this money was largely spent as "cleanup costs" — reducing a bank's losses and liability after a financial incident or lawsuit had already occurred. Recently, though, it's increasingly become "prevention money" — spotting legal risks and heading off problems before a business even launches.
Historically, banks' legal advisory spending has tended to spike sharply whenever a major financial incident or dispute breaks out. According to data from Rep. Shin Jang-sik's office (Rebuilding Korea Party), the five major banks — KB Kookmin, Shinhan, Hana, Woori, and NH Nonghyup — spent about 44.3 billion won on legal advisory fees in 2023, but that figure jumped to 61.8 billion won the following year after the Hong Kong H-index ELS (equity-linked securities) mis-selling scandal broke. These banks are estimated to have spent at least 40 billion won on legal fees again last year.
This isn't just a domestic phenomenon. As banks' overseas operations expand, cases of getting caught up in local lawsuits or facing sanctions from foreign regulators have also increased, driving up demand for legal counsel abroad. Over the past three years, overseas subsidiaries and branches of the five major financial groups have faced about 100 sanctions from local authorities, 83 of which were bank-related. One major bank paid more than 30 million won in foreign-currency legal fees at a single overseas branch last year alone.
Legal advisory costs are rising because financial incidents or disputes tend to generate simultaneous legal needs — from consumer compensation issues to civil and criminal litigation and responding to regulatory inspections and sanctions. Still, there's some criticism of banks — which operate using customer funds — spending large sums on legal fees to reduce their liability or respond to sanctions after an incident has already occurred. At last year's National Assembly audit, lawmakers criticized banks' massive legal spending, with one remarking that it's a structure where the bank makes the mistake and the public foots the bill.
Having paid a steep price through repeated financial incidents and consumer disputes, banks appear to be shifting their approach. Rather than scrambling for a response after a problem surfaces, they're reportedly putting more effort into legal review from the product and service design stage onward, checking upfront whether consumers could be harmed. In particular, since the 2024 Hong Kong H-index ELS scandal, banks' consumer protection responsibilities around product sales have expanded significantly, making it even more important to screen out legal risks in advance.
Rising legal advisory spending at banks isn't necessarily a bad thing in itself. What matters isn't how much a bank spends on law firms, but what that money is spent on. Money spent reducing a bank's liability and avoiding sanctions after an incident has occurred carries a very different meaning from money spent identifying risks and preventing consumer harm before a product ever launches — even though both fall under the same line item of "legal advisory fees." There's no need to automatically begrudge banks spending more on law firms. What's worth keeping an eye on, though, is whether that money is increasingly going toward preventing consumer harm, rather than simply defending the bank's own mistakes.
Han Sang-wook
#Bank #Law firm
Copyright by Asiatoday
Most Read
-
1
Celltrion’s Omlyclo gains ground in major European..

-
2
Trump demands rates fall below 1% as Fed hikes for..

-
3
Hyundai Motor Group breaks ground on integrated st..

-
4
U.S. strikes 3 Iranian oil tankers, Iran vows reta..

-
5
Trump makes $1 trillion bet ahead of midterm elect..

-
6
Iran resumes ballistic missile production, assembl..

-
7
Samsung Electronics, Mistral AI to jointly develop..

PEOPLE


-
Address : In-Young Bldg., 34, Uisadang-daero 1-gil, Yeongdeungpo-gu, Seoul
Copyright by ASIATODAY CO., LTD. All rights resereved